A customer who wants a personal loan should not have to visit a branch, print a salary certificate or wait a week to hear whether they qualify. Everything a lender needs to decide can already be verified digitally in the Kingdom: identity, salary, existing obligations and credit history.
Prestige LOS is our design for that journey, from the first tap to money in the account, and on through repayment and closure.
To be clear from the start: Prestige LOS is a high-fidelity prototype. It is not running in production with any lender. It is complete as a customer journey and ready for a branded pilot with a lender that wants to build on it.
Seven steps, one phone, no branch
The journey starts with eligibility, so nobody is shown an amount they cannot have.
- Sign in and Nafath. A mobile number and one-time code, then identity verified through Nafath in one tap.
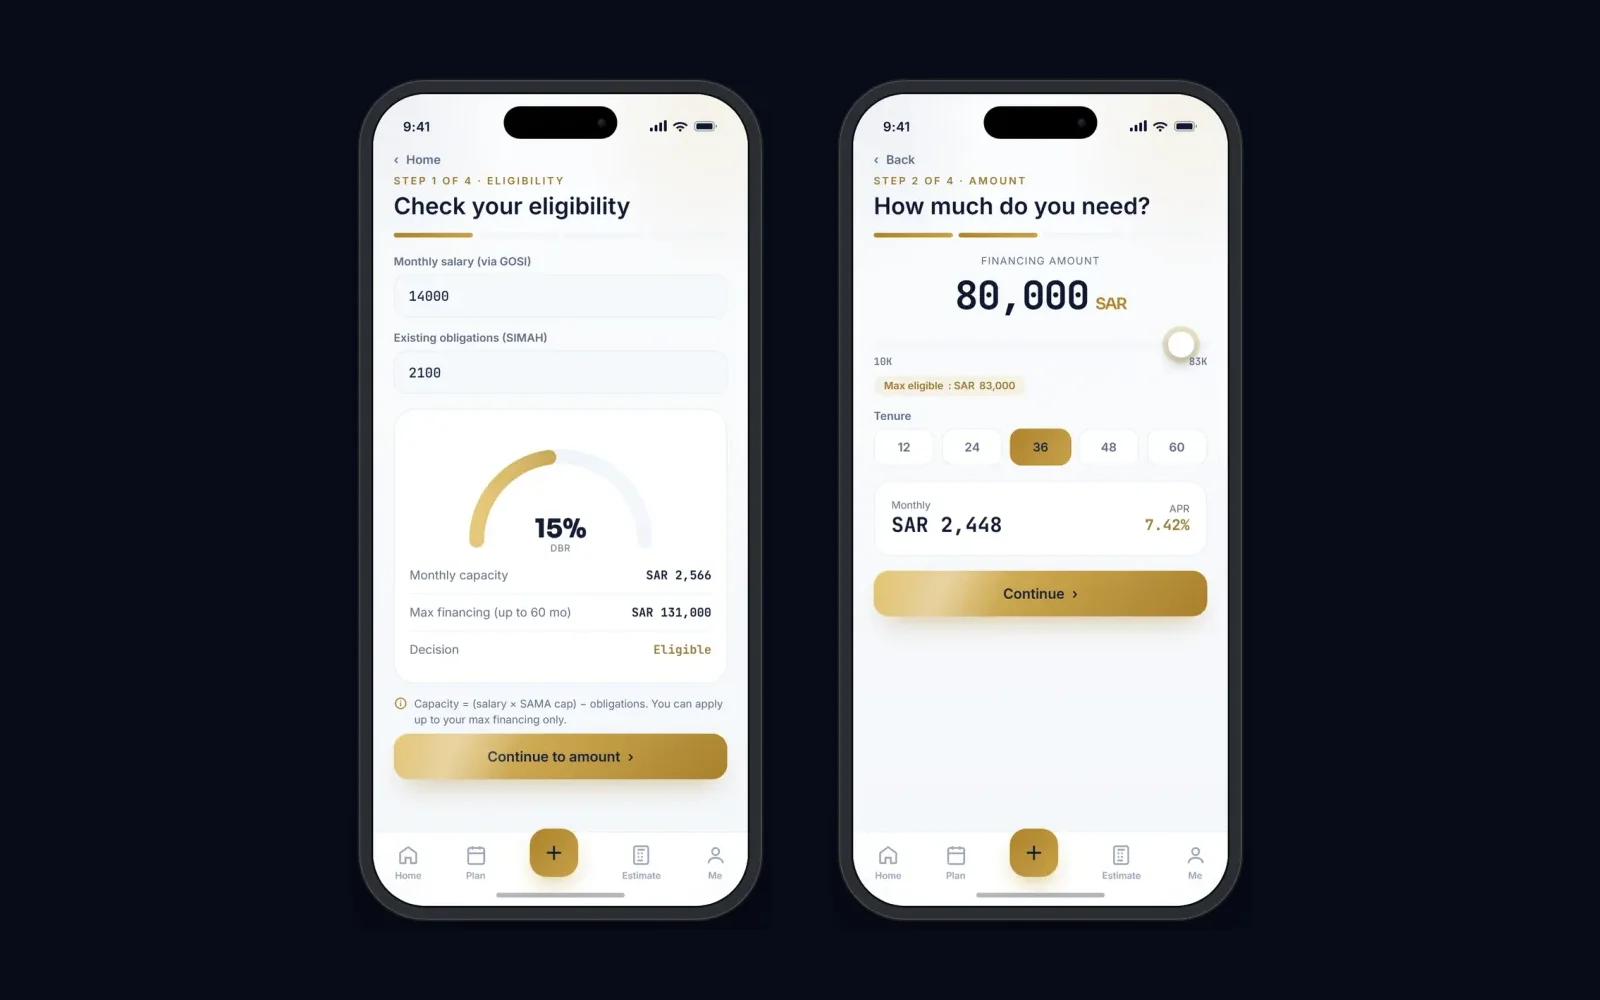
- Instant eligibility. Salary and existing obligations give a debt-burden ratio against the lending cap, and the maximum financing the customer qualifies for.
- Amount and product. The customer chooses up to what they qualify for, with the instalment and effective APR updating live, then picks Murabaha or Tawarruq.
- eKYC and consent. Documents are captured with quality checks, the national address is fetched by location, and each authorisation is approved separately.
- Decide and disclose. Approved, conditionally approved, or declined with guidance, followed by the offer and a full Key Facts Statement.
- E-sign and disburse. The contract is signed through Nafath with an audit record, the IBAN is verified, and the net amount is transferred.
- Service and settle. A living dashboard with the schedule, payments, autopay, early settlement, and a clearance certificate at closure.
Designed around Saudi regulation, not retrofitted to it
The touchpoints that a lender's risk, compliance and Shariah teams look for are part of the journey itself:
- Responsible lending. Debt-burden caps driven by configuration, effective APR and Key Facts disclosure, a cooling-off period, and capped early-settlement cost.
- Murabaha and Tawarruq. Disclosed profit rather than interest, with a rebate on the remaining profit when the customer settles early.
- Verified identity. Nafath and Yakeen identity, SIMAH credit data, PEP and sanctions screening, and quality checks on captured documents.
- Granular consent. Separate, time-stamped consents for the credit bureau, AML, personal-data processing and FATCA, kept with an audit trail.
- Policy, not code. Decisions belong on the server, and regulatory limits come from policy configuration, never hard-coded into the app.
Regulatory and Shariah approval of any live deployment rests with the lender, its regulator and its Shariah board.
Origination is half the product
The same app carries the loan after disbursement: outstanding balance and next payment, a repayment plan, a downloadable amortisation schedule, payments by instalment or in advance, a transparent early-settlement quote, and a clearance certificate at closure. Every screen works in Arabic and English, in light and dark themes, and can carry the lender's brand.
Where it stands
Complete today:
- The full customer journey, from sign-in to closure
- More than 40 screens across origination, servicing and settlement
- Arabic and English, light and dark
- Eligibility, instalment and effective-APR calculations
- Conditional, declined and failed-payment paths, not only the happy path
The build phase, with a lender:
- Live connections to the national services and payment rails (simulated in the prototype)
- A server-side credit decision engine on the lender's policy
- Integration with the lender's core and finance systems
- The lender's brand, products and pricing
- Review with its risk, compliance and Shariah teams
Ready for a branded pilot
We will walk your business, risk, compliance and IT teams through the full journey, and scope what a pilot under your brand would take.